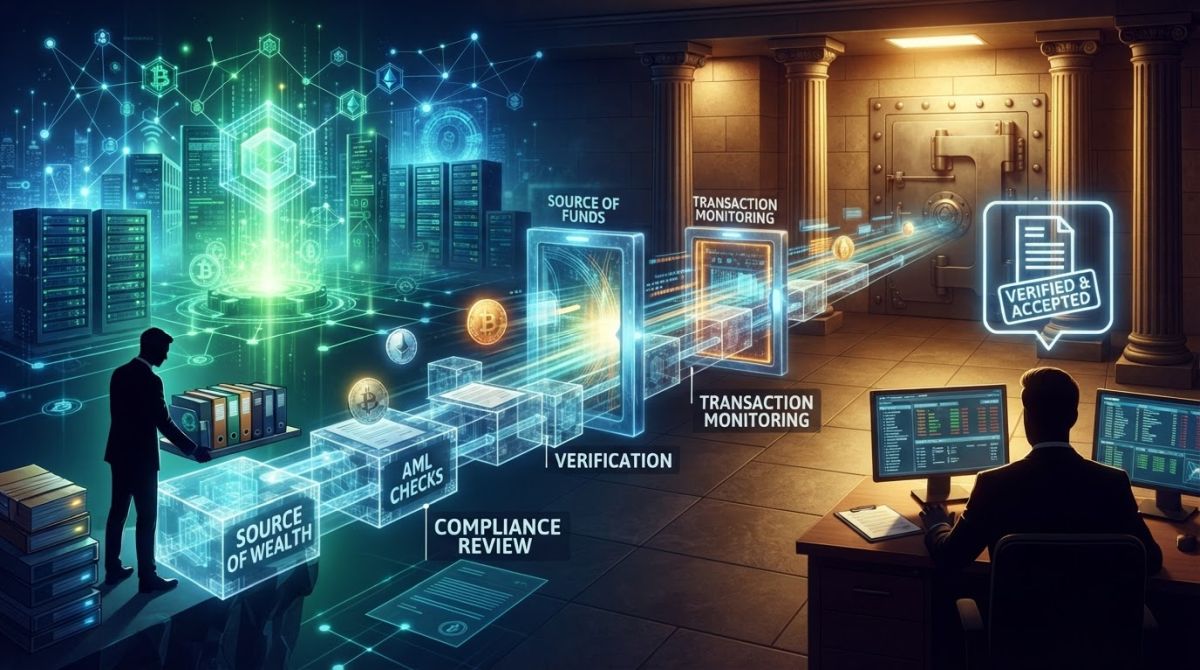
For a bank, “crypto proceeds” is not a complete explanation of where money came from. It identifies an asset category. What matters is the documented economic activity through which the assets were acquired, followed by a traceable path showing how those assets became the government-issued money now entering the banking system.
That distinction explains why a profitable trader can pass an exchange’s know-your-customer checks, sell legitimate assets, initiate a perfectly lawful withdrawal, and still face a rejected wire, an account restriction, or a lengthy compliance review.
After 25 years in traditional finance, I look at a crypto cash-out through two different lenses. An investor sees the economic history: what they bought, how they held it, and why they sold. A bank sees an incoming payment that must fit a documented customer profile and an acceptable transaction history.
The cash-out problem appears when the investor understands that history, but the receiving institution cannot verify it quickly enough.
The bank sees an unusually large payment from a crypto exchange, payment processor, over-the-counter trading desk, or foreign financial institution. It needs to establish whether the transaction fits the customer’s profile, whether the sender is acceptable, whether the assets have sanctions or illicit-finance exposure, whether the customer controls the relevant wallets, and whether the proceeds make sense against the customer’s declared wealth and tax position.
No compliance file is literally bulletproof. Subject to applicable law, a bank may decline lawful business because of its products, operating capabilities, contractual rights, or risk appetite. A complete file does not override a sanctions prohibition or compel an institution to accept a transaction.
My practical objective is more realistic: prepare a file that is so consistent, independently verifiable, and easy to navigate that a compliance analyst does not have to reconstruct years of financial history from screenshots and disconnected transaction hashes.
This guide provides general educational information, not individualized legal, tax, or banking advice. Requirements vary by institution, jurisdiction, customer profile, and transaction.
What a Bank Actually Decides When You Cash Out Crypto
A bank reviewing a substantial crypto cash-out is deciding whether it can understand, verify, and accept the transaction, not whether cryptocurrency is legal in the abstract.
In practice, it needs answers to seven operational questions:
- Who owns the money?
- How did that person originally acquire the wealth used to invest?
- How were the specific crypto assets being sold acquired?
- What happened to those assets on-chain?
- Who is sending the fiat payment, and why is that sender involved?
- Does the amount make sense against the customer’s known financial profile and tax records?
- Can the institution maintain the relationship without unacceptable anti-money laundering, sanctions, fraud, regulatory, or other legally relevant risks?
Under the U.S. customer due diligence framework, covered financial institutions must understand the nature and purpose of customer relationships, develop customer risk profiles, conduct ongoing monitoring, and update customer information on a risk basis.
Source-of-funds and source-of-wealth checks are common tools in enhanced due diligence for higher-value or higher-risk relationships. That does not mean every crypto-related payment requires the same investigation. The scope should reflect the actual risks and the institution’s applicable obligations.
For European banking relationships, the EU anti-money laundering framework established by Directive 2015/849, as amended and implemented through national law, also supports risk-based customer due diligence and enhanced measures in relevant circumstances.
Timing matters here. The newer EU Anti-Money Laundering Regulation and its application timetable generally apply from July 10, 2027. I would not describe that regulation’s general requirements as already applicable to an October 2026 transaction simply because the legislation has entered into force.
A bank can become concerned even when the assets are lawful. Common reasons include:
- The incoming amount is dramatically larger than the account’s previous activity.
- The bank account was opened shortly before the transfer.
- The exchange account, wallet ownership records, and bank account identify different owners.
- The wire comes from a payment processor that was not identified in the file.
- The exchange is licensed in one jurisdiction but is not an acceptable counterparty for the receiving bank.
- The on-chain history includes bridges, decentralized exchanges, mixers, privacy tools, exploited protocols, or high-risk services.
- The customer cannot demonstrate control of the relevant self-custody wallets.
- Exchange CSV files do not reconcile with on-chain activity.
- Tax records do not match the claimed acquisition dates, proceeds, income, or gains.
- The customer divides the withdrawal into repeated smaller payments without a documented operational reason.
- The proceeds economically belong to a company, trust, fund, decentralized autonomous organization, or partnership but are being sent to a personal account.
“Frozen” Can Mean Five Different Things
A bank generally does not freeze a blockchain withdrawal. An exchange or custodian may restrict the movement of crypto assets. A bank may delay, reject, return, restrict, or legally block the associated fiat payment.
Those are different events, with different responses.
| Event | What it usually means | Immediate priority |
|---|---|---|
| Exchange withdrawal hold | The exchange is reviewing wallet ownership, transaction risk, account security, Travel Rule information, or source-of-funds information | Respond through the exchange’s secure portal and provide the requested wallet and transaction evidence |
| Incoming bank wire pending | The receiving bank has not released the payment while fraud, sanctions, operational, or AML checks continue | Obtain a case number, identify the exact wire, and submit a consolidated file |
| Wire rejected or returned | The sending bank, intermediary bank, or beneficiary bank declined to process the payment | Obtain the return reason and payment-tracing information before attempting another transfer |
| Account restricted or closed | The institution has limited services or decided that the relationship no longer fits its lawful risk criteria | Request instructions for returning undisputed funds to an account in the same name, subject to any applicable restrictions |
| Funds legally blocked | A sanctions rule, court order, seizure order, or other legal restriction applies | Engage qualified legal counsel immediately and do not attempt to reroute the assets |
A blockchain analytics alert is not the same thing as a legal obligation to block funds under U.S. sanctions rules.
An analytics alert usually triggers an investigation under the institution’s policies. An actual sanctions block involves a legal prohibition and specific requirements for reporting and handling the property.
The distinction between blocking and rejecting a transaction is also important. As explained in the sanctions compliance guidance for the virtual currency industry, some prohibited transactions must be rejected rather than blocked because they do not involve a property interest that must be blocked.
I would establish which situation applies before discussing the next transfer, the next exchange, or the next bank.
1. Exchange AML Checks and Bank Compliance Are Separate Systems
Passing KYC at an exchange does not create a compliance passport that travels with your money to the bank.
The exchange and the bank are separate regulated institutions. Each is responsible for its own customer due diligence, sanctions controls, transaction monitoring, recordkeeping, and suspicious-activity decisions.
The receiving bank generally cannot see the exchange’s complete KYC file, internal wallet attribution, investigation notes, device history, or reasoning for approving the transaction.
Exchange approval therefore answers a different question from bank approval.
| Compliance question | Exchange perspective | Receiving bank perspective |
|---|---|---|
| Who is the customer? | Can this individual or entity open and use an exchange account? | Does the bank understand the customer, beneficial owners, expected activity, and purpose of the relationship? |
| What activity is expected? | Trading, custody, deposits, withdrawals, staking, or other permitted platform activity | Salary, investment proceeds, business revenue, wealth management, or another declared banking purpose |
| What is monitored? | Crypto deposits and withdrawals, counterparties, wallet exposure, account access, and trading behavior | Fiat payments, counterparties, account turnover, geographic exposure, customer profile, fraud, and sanctions |
| Which transaction is being reviewed? | A crypto transfer or trade within the exchange’s systems | A high-value payment entering the traditional financial system |
| What evidence is available? | Internal KYC data, blockchain analytics, platform history, and account records | Payment messages, customer documents, account history, external records, and the evidence the customer supplies |
| What risk decision is made? | Allow, delay, investigate, restrict, or reject platform activity | Credit the payment, investigate it, return it, restrict the account, or end the relationship |
FinCEN’s guidance on business models involving convertible virtual currencies explains how Bank Secrecy Act obligations apply to covered virtual-currency activities. It does not transfer one institution’s compliance judgment to another.
The broader international baseline appears in the risk-based guidance for virtual assets and virtual asset service providers. Those FATF standards inform national frameworks, but they are not a universal bank-approval process or a substitute for local law.
Source of Funds vs. Source of Wealth
This is the most important distinction in a large crypto cash-out.
Source of funds, or SoF, explains the origin and route of the specific money entering the bank.
Source of wealth, or SoW, explains how the customer accumulated the broader wealth that made the investment possible.
A trade confirmation is part of the source-of-funds evidence. It is not necessarily the complete explanation. Depending on the risk, the bank may need both the events immediately preceding the sale and an earlier acquisition history.
| Concept | Question it answers | Strong evidence | Common failure |
|---|---|---|---|
| Source of funds | Where did this specific incoming amount in USD, EUR, or another currency come from? | Exchange deposit record, blockchain transaction, trade confirmation, fiat balance statement, withdrawal confirmation, and wire record | Providing only a screenshot showing that crypto was sold |
| Source of wealth | How did the customer originally acquire the capital or assets used to build the position? | Employment income, business-sale documents, investment statements, inheritance records, mining records, token-compensation agreements, tax returns, or audited company accounts | Saying “early crypto investor” without evidence of how the original assets were acquired |
| Ownership or control | Does the customer own the exchange account and bank account, and control the relevant wallet? | Account statements, KYC profile, wallet signature, verification transaction, entity documents, and matching legal names | Sending proceeds from a personal exchange account to an unrelated company’s bank account |
| Economic purpose | Why is the transaction happening now, and why is this account receiving the money? | Liquidity plan, property purchase, portfolio diversification, tax payment, business capitalization, or investment mandate | Providing no explanation for a sudden high-value transfer |
Consider a hypothetical investor who used USD 200,000 of salary savings to buy Bitcoin in 2017, moved it into self-custody, and sold part of the position for USD 4 million in 2026.
The investor’s source-of-wealth evidence might include:
- Employment agreements, Forms W-2, pay statements, or tax returns.
- Bank statements showing accumulated savings.
- The original bank transfer to the exchange.
- Evidence that the initial investment was financially plausible against the investor’s income and net worth.
The source-of-funds evidence for the USD 4 million might include:
- The original exchange purchase records.
- The withdrawal transaction from the exchange into self-custody.
- Evidence of control over the self-custody wallet.
- The on-chain path from the original withdrawal to the current wallet.
- The deposit transaction into the exchange used for the cash-out.
- The exchange’s deposit-credit confirmation.
- The sale confirmation or OTC execution confirmation.
- The exchange’s fiat balance statement.
- The outgoing wire confirmation.
- The receiving bank account details.
A bank may accept a narrower review in a lower-risk case. A private bank, international bank, correspondent bank, or institution reviewing a particularly large transaction may go considerably deeper.
What I would not do is assume that the final sale receipt answers every question about the money.
When Source-of-Wealth Checks Become More Extensive
The more complex the ownership, acquisition history, or transaction route, the more important source-of-wealth evidence becomes.
Expect a more demanding review when one or more of these circumstances apply:
- The transaction is large relative to the customer’s known income or account history.
- The customer is a politically exposed person or is connected to one.
- The wealth originated in a higher-risk jurisdiction.
- The assets came from a business sale, inheritance, gift, trust, offshore company, DAO, or private token allocation.
- The customer used multiple exchanges, OTC desks, self-custody wallets, bridges, or decentralized finance protocols.
- The assets spent long periods outside regulated platforms.
- The account is part of a private banking or wealth-management relationship.
- The customer claims early mining, anonymous purchases, or peer-to-peer acquisitions for which documentation is incomplete.
- The transaction involves an entity whose beneficial ownership is not immediately clear.
The bank wants a documented chain of economic ownership, not just evidence of a profitable final trade.
2. How Blockchain Risk Scoring Actually Works
Blockchain risk scores are investigation tools, not universal verdicts that a wallet is “clean” or “dirty.”
Tools such as Chainalysis KYT transaction monitoring, Elliptic wallet screening and explainable risk scoring, and TRM’s expanded indirect-exposure analysis provide attribution data, exposure information, behavioral indicators, and configurable risk assessments.
The exchange, bank, custodian, stablecoin issuer, or payment provider decides how those results affect its actions. Not every institution runs the same tools directly, and not every provider supports the same chains, assets, or tracing methods.
A typical monitoring process has six layers:
- On-chain data collection. The system collects transactions, token transfers, smart-contract interactions, bridge events, and other supported blockchain data.
- Address clustering and attribution. Addresses may be grouped or associated with exchanges, payment services, sanctioned persons, darknet markets, ransomware groups, mixers, scams, bridges, decentralized exchanges, gambling services, or other categories.
- Direct-exposure analysis. The system assesses whether the screened wallet sent funds directly to, or received funds directly from, an attributed service or address.
- Indirect-exposure analysis. The system examines whether value passed through one or more intermediary wallets before reaching or leaving an attributed service.
- Behavioral analysis. Rules may identify rapid movement, peel-chain patterns, cross-chain transfers, repeated transfers near thresholds, high transaction velocity, newly created wallets, asset swaps without an apparent economic purpose, or interactions associated with layering.
- Institution-defined thresholds. The institution determines which categories, amounts, percentages, directions, and levels of exposure trigger an alert.
A peel chain, for example, generally involves repeated transactions that send part of a balance onward while moving the remainder to another address. That pattern can have legitimate explanations, but it can also be relevant to an investigation.
The same wallet can therefore receive different treatment at different institutions. One exchange may tolerate limited, remote exposure to a gambling service. Another may escalate any such exposure. A sanctions match may be treated very differently from an old, low-value, indirect connection to a mixer.
The FATF red flags for virtual-asset money laundering and terrorist financing emphasize transaction patterns, anonymity-enhancing technologies, mixers, unexplained transaction sizes and frequency, higher-risk locations, customer profiles, and inconsistencies in source of funds or wealth.
The important point is context. A risk indicator is a reason to ask questions, not a substitute for answering them.
A Risk Score Is a Starting Point, Not Proof of Guilt
A high score does not establish that the wallet owner committed a crime.
Possible explanations include:
- The wallet received funds from an exchange hot wallet or cluster that also handled unrelated high-risk activity.
- A small portion of the wallet’s activity has remote indirect exposure.
- A scammer or spammer sent an unsolicited dust transaction.
- An address was attributed to a particular person or service only after the customer transacted with it.
- A bridge or decentralized-exchange liquidity pool combined activity from many users.
- The analytics provider’s attribution is incomplete or disputed.
- The wallet interacted with a service before it was sanctioned or classified as high risk.
Indirect-exposure figures also depend on the tracing methodology. They are not necessarily a literal identification of the same units moving unchanged through every intermediate transaction.
My response would not be to hide the route. It would be to quantify and explain it.
A useful independent analytics report should identify:
- The addresses screened.
- The screening date and time.
- Direct and indirect exposure.
- The amount and percentage of affected value.
- The number of intermediary steps, often called hops.
- The attributed service or risk category.
- The direction of exposure.
- Relevant transaction hashes.
- Whether the exposure predates a sanctions designation.
- Whether the exposure is economically material.
- The analyst’s conclusion and the limitations of the analysis.
A one-page screenshot with a green score is weak evidence on its own. An explainable report supported by transaction-level data is considerably more persuasive.
Neither report guarantees bank acceptance. The receiving institution still makes its own decision.
Why Decentralized Exchange Activity Can Trigger Alerts
Using a decentralized exchange, or DEX, is not inherently unlawful. The compliance challenge is often attribution.
A centralized exchange can usually identify its own customer and provide records of that customer’s activity. A DEX smart contract generally executes a swap without identifying the economic participants behind the available liquidity.
That raises several questions:
- Which wallet initiated the swap?
- Which assets entered the contract?
- Which assets came out?
- Was the transaction routed through an aggregator?
- Did the liquidity pool have exposure to stolen or sanctioned assets?
- Were fees paid from a different wallet?
- Did the swap happen immediately before or after a bridge transaction?
- Does the activity resemble ordinary portfolio management or rapid layering?
For a complex DEX history, I would document each material swap as an economic event, not merely as a hash.
Include:
- Date and time in UTC.
- Originating wallet.
- Protocol and contract.
- Asset and quantity sent.
- Asset and quantity received.
- Gas and protocol fees.
- Fiat value at the time of the transaction.
- Transaction hash.
- Business or investment purpose.
- Tax treatment applied in the relevant jurisdiction.
A liquidity-pool interaction does not automatically mean that every user’s assets are illicit. It does mean the reviewer may need more context than a conventional exchange statement provides.
Why Bridge Transactions Add Compliance Work
A bridge moves value between blockchains, so the audit trail must connect both sides of the transfer.
Bridges have legitimate uses, including liquidity management, staking, gaming, settlement, and access to protocols on different networks.
Cross-chain movement is also a recognized laundering technique. A reviewer may need to establish that assets deposited on one chain correspond to assets received on another, particularly when wrapped tokens, relayers, aggregators, or liquidity networks are involved.
The 2026 FATF report on regulatory challenges in decentralized finance emphasizes a functional, risk-based approach to DeFi arrangements and the risks that arise when activity operates through decentralized infrastructure.
For each bridge event, provide:
- Source-chain transaction hash.
- Destination-chain transaction hash.
- Source and destination wallet addresses.
- Bridge provider and contract.
- Assets sent and received.
- Amounts, fees, and slippage.
- Time difference between the two sides.
- Any minting or burning of wrapped tokens.
- The next transaction showing where the bridged assets went.
- A brief statement of economic purpose.
Do not describe a 12-step cross-chain route as “moved to another wallet.”
That wording leaves the reviewer with the hardest part of the investigation. At worst, it can look like an attempt to conceal the route.
Why Self-Custody Wallets Require Additional Evidence
A self-custody wallet is not automatically suspicious, but its identity and ownership cannot be established merely by naming a regulated account provider.
There is no regulated wallet host that can supply the holder’s customer-identification records on their behalf. The institution may therefore need additional evidence from the customer.
Compliance may need to establish:
- Who owns or controls the address.
- Whether the wallet belongs to the bank’s customer.
- Whether another person can direct transactions.
- Whether the wallet is personal, corporate, trust-owned, or controlled through a multisignature arrangement.
- Whether the wallet history matches the customer’s explanation.
- Whether third-party funds entered the wallet.
The EBA risk-factor guidance for crypto-asset service providers provides a broader risk-based framework for assessing customers, products, transaction channels, and geographic exposure. The relevant question is the overall risk and the evidence available, not simply whether a wallet is self-hosted.
Under the EU rules governing information accompanying crypto-asset transfers, relevant providers must take adequate measures to assess ownership or control in specified transfers exceeding EUR 1,000 that involve a self-hosted address.
The assessment concerns the originator or beneficiary, as applicable to the direction and circumstances of the transfer. The EUR 1,000 provision should not be mistaken for a general exemption from transfer-information requirements below that amount.
The EBA guidance on Travel Rule information requirements addresses implementation, including methods for assessing ownership or control.
The Travel Rule concerns identifying information that must accompany relevant transfers. It is separate from the blockchain transaction itself.
Useful evidence may include:
- A digitally signed message produced using the relevant wallet’s key.
- A verification transaction using an amount specified by the provider.
- A dated wallet-interface capture showing the address and account name, if the institution accepts it.
- Hardware-wallet purchase and setup records.
- A wallet inventory signed by the individual or an authorized company representative.
- Multisignature configuration and signer documentation.
- A custody or agency agreement if another party controls the keys.
I make an important distinction here: a valid wallet signature can demonstrate control of a key at the time of signing. It does not, by itself, prove historical control, exclusive control, or legal ownership of every asset associated with the wallet.
Hardware receipts and screenshots are supporting evidence, not substitutes for stronger proof.
Only complete a verification procedure through an independently confirmed institutional channel. Do not blindly sign transactions, token approvals, or unreadable messages presented as “compliance verification.”
Never disclose a seed phrase, raw private key, wallet backup containing secret material, or security credential. Legitimate compliance verification does not require possession of your private keys.
Why Mixer Exposure Can Stop an Otherwise Legitimate Cash-Out
Mixers and tumblers are significant AML risk categories because they are designed to break or complicate transaction traceability. Depending on the service and circumstances, sanctions issues may also arise.
FATF, FinCEN, OFAC, and blockchain analytics providers treat mixer exposure as an important investigative factor. That does not mean every mixer interaction creates the same legal or compliance outcome.
Risk depends on context:
- Direct interaction is generally more significant than remote indirect exposure.
- Recent exposure may be treated differently from historical exposure.
- A material percentage of the funds raises different concerns from a negligible amount.
- Exposure to a sanctioned service differs from exposure to a non-sanctioned privacy service.
- Incoming exposure differs from an intentional outgoing deposit into a mixer.
- Exposure before designation may require a different analysis from exposure after designation.
Sanctions status can change. The relevant analysis may need to consider both the transaction date and the service’s current status.
There is no universal legal rule under which every downstream unit of cryptocurrency becomes permanently “tainted.” There is also no guarantee that a bank will accept funds simply because a mixer was several hops away.
If mixer exposure exists:
- Do not route assets through additional wallets to make the connection less visible.
- Do not omit relevant addresses from the wallet inventory.
- Quantify the exposure by amount, percentage, date, direction, and number of hops.
- Explain the economic circumstances truthfully.
- Obtain professional forensic analysis for material exposure.
- Consult sanctions or financial-crime counsel if the service was sanctioned or the assets may be connected to criminal proceeds.
A better explanation can resolve uncertainty. Additional concealment generally creates more of it.
Structuring and Smurfing: How to Make a Compliance Review Worse
Deliberately splitting a crypto cash-out to avoid reporting or scrutiny can create a serious problem even when the underlying assets are legitimate.
Under U.S. law, structuring generally involves arranging or breaking up transactions with the intent to evade applicable Bank Secrecy Act reporting or recordkeeping requirements.
Not every installment payment is structuring. Intent, the applicable requirement, and the surrounding facts matter.
“Smurfing” commonly describes distributing activity across multiple people, accounts, or transactions to make the overall movement less apparent.
From a practical banking perspective, intentionally dividing a large cash-out to stay below assumed compliance thresholds is one of the worst strategies an investor can choose.
Monitoring systems may aggregate activity across:
- Multiple days.
- Multiple accounts.
- Multiple branches or banking channels.
- Multiple exchange accounts.
- Multiple wallets.
- Related individuals or entities.
- Repeated transfers of similar amounts.
- Transfers just below platform limits or monitoring thresholds.
FinCEN’s advisory on illicit activity involving convertible virtual currency identifies patterns such as repeated below-threshold activity, rapid conversions, multiple accounts, and smurfing as potential red flags.
A wire transfer does not become invisible because it stays below USD 10,000.
The familiar USD 10,000 threshold primarily concerns currency transaction reporting for transactions involving physical cash, subject to the applicable aggregation rules. Suspicious-activity monitoring is much broader and is not avoided by sending smaller wires.
A Pattern That Is Difficult to Defend
An investor wants to withdraw USD 2 million and sends:
- Forty transfers of approximately USD 50,000.
- Through three exchanges.
- To four bank accounts.
- Over two weeks.
- Without notifying any institution of the overall plan.
- Using different sender names and payment processors.
Even if every dollar is legitimate, the pattern can look like fragmentation designed to avoid scrutiny.
The customer has turned one explainable transaction into a network of transactions that requires a broader investigation.
A Legitimate Installment Schedule
Installments can be entirely reasonable when they result from:
- Exchange withdrawal limits.
- OTC settlement terms.
- Market liquidity.
- Counterparty credit limits.
- A bank-approved settlement schedule.
- Currency-conversion requirements.
- A documented asset-sale agreement.
The defensible approach is to disclose the expected total, the reason for installments, the number of payments, anticipated dates, sender, and receiving account before the first transfer.
I would not ask a bank:
What amount can I send without triggering compliance?
I would ask:
I expect total proceeds of approximately USD 2 million, likely in four scheduled transfers because of a documented exchange settlement limit. What information should I provide before initiating the transfers?
Those questions communicate very different intentions.
3. Build the Banking Route Before You Sell
The right cash-out bank is the institution that can accept and understand your specific transaction, not necessarily the one that advertises itself as crypto-friendly.
Marketing matters less than the institution’s license, payment infrastructure, account structure, compliance capabilities, and willingness to handle the actual facts.
I would establish the receiving route before creating a large fiat balance that needs somewhere to go.
Choosing the Banking Channel
| Channel | Advantages | Limitations | Best use |
|---|---|---|---|
| Traditional retail bank | Familiar accounts, low costs, established payment access | Limited relationship management, rigid consumer monitoring, little capacity to review complex on-chain documentation in advance | Smaller or straightforward proceeds consistent with existing account history |
| Private bank or wealth manager | Dedicated relationship manager, experience with high-net-worth customers, better escalation routes | Detailed source-of-wealth review, minimum asset requirements, conservative onboarding | High-net-worth investors with documented wealth and recurring liquidity needs |
| Commercial bank | Treasury services, entity accounts, substantial payment capacity | Requires a genuine business purpose, beneficial ownership review, financial statements, and expected activity | Trading companies, funds, family offices, or operating businesses receiving their own proceeds |
| Specialist digital-asset bank | Familiarity with exchanges, custody, stablecoins, and blockchain analytics | Limited geographic reach, concentration risk, changing correspondent relationships | Recurring digital-asset activity supported by strong institutional documentation |
| Electronic money institution or payment institution | Potentially faster onboarding and familiarity with crypto businesses | May not be a bank, may not provide deposit insurance, and may rely on pooled or safeguarded accounts | Operational payment flows where the account’s legal structure is fully understood |
| Regulated OTC desk with a banking partner | Large-block execution, documented settlement, named counterparties | Enhanced initial diligence, minimum trade sizes, fees, and counterparty concentration | Large liquidations where exchange order books or withdrawal arrangements are unsuitable |
When using an electronic money institution or payment provider, establish whether your balance represents:
- A bank deposit in your own name.
- Safeguarded electronic money.
- Pooled client funds.
- A claim against the payment institution.
- Funds eligible for deposit insurance.
- Funds subject to withdrawal, settlement, or correspondent-bank restrictions.
Those categories can overlap operationally, but their legal protections are not interchangeable.
An account number and a polished app do not make a provider equivalent to an insured commercial bank. Safeguarding is not the same protection as deposit insurance.
Preserve Ownership Consistency Along the Route
The simplest route generally keeps the same legal owner identifiable from start to finish:
- The individual or entity owns the assets.
- The same individual or entity controls the wallet.
- The exchange or OTC account is in that owner’s legal name.
- The receiving bank account is in the same legal name.
- The fiat payment comes from the disclosed exchange, OTC desk, or documented payment partner.
Name and ownership mismatches create immediate questions.
Examples include:
- A personal wallet funding a company’s exchange account.
- A company exchange account sending money to a personal bank account.
- Trust assets being liquidated through a trustee’s personal account.
- An exchange withdrawal being sent to a spouse’s account.
- An OTC desk receiving crypto from one person and wiring proceeds to another.
- A DAO contributor sending token compensation directly to an unrelated LLC.
- A family-office account receiving proceeds beneficially owned by one of its clients.
Some of these arrangements can have legitimate explanations. They require documentation, not an assumption that everyone involved will understand the relationship.
If ownership genuinely changed, document the change through the appropriate contribution agreement, assignment, gift agreement, trust instrument, board resolution, loan agreement, distribution authorization, or tax treatment.
Verify the Exchange or OTC Counterparty
Before transferring assets, verify:
- The entity’s legal name.
- Its authorization, registration, or licensing status.
- The jurisdiction from which it serves you.
- Whether it operates under a current permission rather than an expired transitional arrangement.
- The name that will appear as the fiat sender.
- Whether a separate payment processor or banking partner sends withdrawals.
- Whether the provider supports payments to your bank and jurisdiction.
- Its Travel Rule and self-custody wallet requirements.
- Fiat withdrawal and settlement limits.
- Whether it issues official account statements and trade confirmations.
- Whether its records include transaction hashes and payment references.
- Whether the receiving bank accepts payments from that counterparty.
For EU providers, the maximum MiCA transitional endpoint of July 1, 2026, has passed. Some member states used shorter periods.
Under the Markets in Crypto-Assets Regulation and its transitional provisions, I would verify the provider’s current authorization or other applicable legal basis for providing the services. An old national registration is not, by itself, proof of current permission.
The July 2026 FATF review of virtual-asset regulation and supervision also highlights continuing gaps in licensing, supervision, and practical implementation across jurisdictions.
“Regulated somewhere” is not the same as “currently authorized to serve me and acceptable to my receiving bank.”
Use One Primary Cash-Out Route
For a large liquidation, unnecessary complexity is the enemy.
A straightforward route usually uses:
- One main wallet or a clearly mapped group of wallets.
- One regulated exchange or OTC desk.
- One fiat currency.
- One receiving bank.
- One clearly identified beneficial ownership structure.
- One disclosed transaction purpose.
A backup bank that has already been informed of the activity can make sense for operational resilience. Establish that relationship early.
It should not become a way to divide the same cash-out among institutions without disclosing the total plan.
A nominal test transfer may be appropriate to confirm payment instructions and routing. Identify it as a test, obtain approval where practical, and follow it with the disclosed main transfer.
Repeated “tests” can start to look like fragmentation.
A Practical Timeline Before Withdrawing Crypto Proceeds
Start the banking and documentation work before the sale, ideally several weeks before the money needs to arrive.
The following is a planning schedule, not a regulatory deadline. Complex ownership structures or incomplete historical records may require more time.
| Timing | Action |
|---|---|
| 60 to 45 days before | Choose the bank and cash-out provider, refresh KYC information, confirm account ownership, and begin reconstructing transaction history |
| 45 to 30 days before | Complete the source-of-wealth file, wallet inventory, exchange exports, tax reconciliation, and preliminary blockchain screening |
| 30 to 21 days before | Contact the relationship manager or bank support team and disclose the expected transaction |
| 21 to 14 days before | Submit the executive summary and requested evidence through the bank’s approved secure channel |
| 14 to 7 days before | Resolve questions, confirm the expected sender name, and finalize the transfer schedule |
| 7 to 2 days before | Complete final wallet-risk screening, independently verify wire instructions, and stop making unnecessary changes to the transaction route |
| Execution day | Preserve exchange deposit, trade, fiat balance, and withdrawal records as soon as they are created |
| First five business days afterward | Monitor messages and respond to documentation requests the same business day where possible |
I would not liquidate first and only then ask whether the bank accepts the proceeds.
Once the money is already moving, the institution is working within payment-processing and investigation timelines rather than a planned onboarding process.
When to Notify Your Bank in Advance
Contact the bank before initiating the transaction when:
- The incoming amount substantially exceeds normal account activity.
- The payment comes from a crypto exchange, OTC desk, foreign bank, or payment processor.
- The proceeds involve self-custody wallets.
- The amount is likely to require private banking review or enhanced due diligence.
- The sender’s name will differ from the exchange’s consumer-facing brand.
- The payment will arrive in installments.
- You have recently changed occupation, residence, tax status, or business structure.
Use the relationship manager, private banker, treasury officer, compliance-document portal, or another channel designated by the institution.
An informal assurance from a branch employee may be operationally useful. It is not necessarily binding compliance approval.
A concise notice could read as follows. Use the ownership statements only if they accurately describe your circumstances, and adapt them for an entity or trust.
Subject: Expected investment proceeds from [counterparty legal name]
I expect to receive approximately USD [amount or range] between [dates] from [legal name of exchange, OTC desk, or payment provider].
The funds will represent proceeds from the sale of digital assets held for investment. I am the beneficial owner of the assets, exchange account, and receiving bank account.
The position was originally funded from [employment income, business-sale proceeds, inheritance, or another source], beginning in [year]. The relevant assets were subsequently held in self-custody and transferred to [cash-out provider] for liquidation.
I have prepared an executive summary, source-of-wealth evidence, exchange records, wallet-control evidence, an on-chain transaction schedule, trade confirmations, and a tax reconciliation.
Please confirm:
- Whether the expected sender is acceptable.
- Which documents should be submitted before initiating the transfer.
- The secure submission channel and reference number.
- Whether the expected activity on my account should be updated.
- Whether any transfer-size, currency, or settlement requirements apply.
Do not ask for an absolute guarantee that the transaction will clear.
No frontline employee can eliminate later sanctions, fraud, correspondent-bank, or AML review. The objective is to update the customer profile, identify unacceptable routes, and create an internal record before the money arrives.
4. How to Build a Bank-Ready Crypto Compliance File
A strong compliance file is not the largest file. It is the file that lets an unfamiliar analyst reach an informed conclusion with the least reconstruction.
I would build the package around eight qualities:
- Self-contained: The reviewer should not need 20 follow-up emails.
- Chronological: The sequence of events should be obvious.
- Reconciled: Asset quantities and fiat amounts should connect.
- Independently verifiable: Primary documents and blockchain records should support the narrative.
- Ownership-consistent: The relevant legal and beneficial ownership should remain traceable.
- Explicit about exceptions: Missing records and risk exposures should be disclosed rather than hidden.
- Tax-consistent: The explanation should not contradict tax returns, information reports, or accounting records.
- Securely delivered: Sensitive documents should go through an approved channel.
Recommended Folder and File Structure
Use a numbered structure that preserves the intended order after download:
00_Executive_Summary_and_Index
01_Identity_and_Account_Ownership
02_Source_of_Wealth
03_Initial_Fiat_Transfer
04_Exchange_Acquisition_Records
05_Wallet_Ownership_and_Control
06_On_Chain_Audit_Trail
07_Cash_Out_Trade_and_Settlement
08_Tax_and_Accounting_Reconciliation
09_Entity_Trust_or_Fund_Documents
10_Exceptions_and_Explanations
Use ISO-format dates in filenames:
2017-06-14_Bank_Wire_to_Exchange.pdf
2017-06-15_Exchange_BTC_Purchase.csv
2017-07-02_Exchange_Withdrawal_TXID.pdf
2026-09-20_Exchange_Deposit_Confirmation.pdf
2026-09-21_Trade_Confirmation.pdf
Preserve original CSV, PDF, JSON, email, and other exports or statements. Do not replace source records with edited spreadsheets.
Create a separate reconciliation workbook that points back to the originals.
For a high-value file, consider preserving file integrity by generating a manifest of SHA-256 hashes for the original exports. A hash does not prove that the underlying records are true, but it can help show that the files have not changed since the manifest was created.
Review exports before sharing them. Account data belongs in the compliance package when relevant. Private keys, seed phrases, recovery material, and authentication secrets do not.
Write a One- to Two-Page Executive Summary
The executive summary should let a compliance reviewer understand the transaction in less than three minutes.
This is the most important document in the package. The supporting exhibits prove the facts, but the summary tells the analyst where to look and why those facts matter.
Page one should cover:
- Customer identity and banking relationship.
- Expected transaction.
- Source of funds.
- Source of wealth.
- Ownership statement.
- Summary of the on-chain route.
- Tax status.
- Material risk disclosures.
Page two, if needed, should include:
- A short chronology.
- A numbered flow of funds.
- A document index.
- Contact details for the customer, accountant, attorney, or forensic specialist.
For a standard WordPress page or a bank document, a simple numbered flow is often clearer than a complex diagram.
For example:
- Documented employment savings accumulated in the investor’s bank account.
- Fiat transferred to the original exchange.
- Bitcoin purchased and withdrawn into self-custody.
- Relevant wallet activity documented.
- Bitcoin deposited with the cash-out exchange.
- Sale completed and fees deducted.
- Disclosed payment partner sent the net proceeds.
- Receiving bank credited the investor’s account.
Executive Summary Template
Adapt this template to the actual owner and facts. A trustee, company officer, or authorized signatory should not claim personal ownership of assets held for another person or entity.
Date: [Date]
To: [Bank, department, or relationship manager]
Subject: Source of funds and source of wealth for expected digital-asset proceeds
Customer
My name is [legal name]. I have held the account ending in [last four digits] since [date]. My occupation or principal business activity is [occupation or activity]. I reside in [jurisdiction] and am tax resident in [jurisdiction].
Expected transaction
I expect an incoming [wire or other payment method] of approximately [amount and currency] around [date]. The sender is expected to appear as [exact legal sender name]. The payment represents proceeds from the sale of [asset and quantity] through [regulated exchange or OTC desk].
Source of funds
The incoming fiat funds arise from the sale of [asset] on [date]. The assets were deposited with [exchange] from wallet [abbreviated address]. The deposit transaction was [transaction hash]. The exchange credited [quantity], executed the sale for [gross amount], deducted [fees], and approved a fiat withdrawal of [net amount].
Source of wealth
The initial investment capital came from [employment income, business sale, inheritance, investment proceeds, mining, token compensation, or another source]. The relevant capital was accumulated between [dates]. Supporting banking, employment, legal, and tax records are attached.
Ownership
I am the beneficial owner of the initial capital, relevant wallets, exchange account, digital assets, and receiving bank account. Any entity or trust involved is described in the ownership appendix.
On-chain history
The assets were acquired through [exchange or method], beginning in [year]. They were held or used through [brief description of self-custody, staking, DEX, bridge, or other activity]. A transaction-level schedule and address inventory are attached. Material DEX and bridge interactions and relevant risk exposures are separately identified.
Tax and accounting
The transaction has been reported or will be reported in [jurisdiction] under the applicable tax treatment. The attached reconciliation connects exchange records and on-chain activity to the relevant tax or accounting records. [CPA or tax adviser] can address technical questions with my authorization.
Material disclosures
[Describe missing records, defunct exchanges, mixer proximity, bridge use, third-party transfers, payment processors, or other circumstances that could otherwise surprise the reviewer.]
Supporting documents
The attached index identifies each exhibit and the fact it supports.
Contact
Please direct documentation requests to [name and secure contact channel], quoting reference [case or relationship number].
Avoid technical jargon that does not help the decision.
The cover letter is not the place to explain every smart contract. It should identify the economic events and direct the reviewer to the appropriate exhibit.
Build a Master Transaction Reconciliation
A master reconciliation connects the bank records, exchange records, and blockchain records into one chronological account of the money.
The file should include a transaction ledger with enough detail to explain both the financial movements and the supporting evidence.
| Field | What to record |
|---|---|
| Sequence number | Chronological step in the flow of funds |
| Date and time | UTC for on-chain events and the relevant statement or processing date for banking events |
| Event type | Bank transfer, purchase, withdrawal, swap, bridge, staking event, deposit, sale, or fiat withdrawal |
| Source | Bank, exchange account, or wallet |
| Destination | Bank, exchange account, wallet, protocol, or contract |
| Asset | Fiat currency or digital asset |
| Gross quantity | Amount before fees |
| Fee | Bank, exchange, network, gas, bridge, or trading fee |
| Net quantity | Amount after fees |
| Fiat value | Value at the relevant transaction time |
| Identifier | Wire reference, exchange order ID, transaction hash, or payment-tracing identifier |
| Evidence file | Exact filename supporting the event |
| Explanation | Economic purpose or exception note |
Reconcile quantities, not just fiat values. Market movements can make fiat-only comparisons misleading.
For each asset and the position being reconciled, I would use this sequence:
- Start with units acquired.
- Subtract units previously sold.
- Subtract units spent as fees.
- Add units received through staking, mining, airdrops, or income.
- Record units added or removed through swaps and bridge conversions.
- Account separately for other documented transfers or disposals.
- Subtract units still held outside the current liquidation.
- Confirm that the remaining units match the amount deposited for the current sale.
The additional treatment of retained holdings matters when only part of a position is being sold.
Where exact agreement is impossible because of gas, slippage, rebasing tokens, liquidity-provider positions, wrapped assets, or protocol losses, quantify the difference and explain it.
Step 1: Prove the Original Fiat Entry
Include:
- Bank statements identifying the investor and account.
- The wire, ACH, card, or other payment confirmation to the exchange.
- The exchange’s deposit confirmation.
- The exchange account statement showing the fiat credit.
- Evidence of the capital’s origin, such as salary, business proceeds, inheritance, or the sale of another investment.
Do not over-redact the documents.
Where appropriate, you may remove unrelated transactions or full account numbers, subject to the bank’s requirements. Retain enough information to verify:
- Account holder name.
- Financial institution.
- Statement period.
- Account ending digits.
- Relevant transaction.
- Date.
- Amount.
- Counterparty.
- Page numbering.
Clearly mark redactions.
A statement cropped so narrowly that the reviewer cannot verify its owner or statement period is weak evidence.
Step 2: Prove the Crypto Acquisition
Include:
- Official exchange account statement.
- Trade confirmations.
- Order and execution history.
- Deposit and withdrawal history.
- Original CSV exports.
- Relevant invoices or OTC confirmations.
- The exchange account’s ownership or profile page.
- Transaction hashes for withdrawals into self-custody.
Screenshots should supplement official exports, not replace them.
If the assets were acquired through multiple purchases, group those purchases in a schedule while retaining the evidence for each transaction.
A portfolio chart showing today’s balance does not establish how the assets were acquired.
Step 3: Map the On-Chain History
Create an address register that identifies ownership, purpose, and supporting evidence.
| Address or account | Network | Owner | Wallet type | Period used | Purpose | Ownership or control evidence |
|---|---|---|---|---|---|---|
| Abbreviated address | Bitcoin | Individual investor | Hardware wallet | 2017 to 2026 | Long-term holding | Signed message and withdrawal history |
| Abbreviated address | Ethereum | Investment LLC | Multisignature wallet | 2021 to 2026 | DeFi and staking | Entity resolution and signer records |
| Exchange account ID | Multiple networks | Individual investor | Hosted account | 2026 | Liquidation | Exchange statement |
For Bitcoin, remember that a wallet may use many receiving and change addresses. One visible address is not necessarily the entire wallet history.
The on-chain appendix should then show:
- Transfers between the customer’s own wallets.
- Transfers to and from exchanges.
- DEX swaps.
- Bridge events.
- Wrapped-token issuance and redemption.
- Staking deposits and rewards.
- Liquidity-provider deposits and withdrawals.
- NFT or token sales.
- Lending and borrowing.
- Airdrops.
- Mining or validator rewards.
- Smart-contract exploit losses or recoveries.
- Third-party receipts.
Label transfers between your own wallets as internal transfers.
Otherwise, the reviewer may interpret them as unexplained third-party transactions.
Step 4: Prove Wallet Ownership or Control
Use the strongest method supported by the wallet and requested by the institution:
- Cryptographic message signature.
- Verification transaction performed according to the provider’s instructions.
- Transaction history connecting an exchange withdrawal to the wallet.
- Hardware-wallet account export that excludes secret key material.
- Multisignature signer records.
- Custody agreement.
- Company board or manager resolution.
- Trust instrument and trustee authority.
A wallet screenshot is generally weaker evidence because it can be altered and may not demonstrate control of the private key.
I would also separate the questions being proved. A signature may demonstrate key control. An entity resolution, trust instrument, or custody agreement may be needed to establish who legally owns the assets and who is authorized to act.
Step 5: Document the Cash-Out Deposit and Sale
Include:
- Deposit address issued by the exchange.
- Blockchain transaction hash.
- Exchange deposit confirmation.
- Number of confirmations or relevant finality status.
- Credited amount.
- Any fee-related difference.
- Trade execution or OTC confirmation.
- Execution price.
- Gross proceeds.
- Trading and service fees.
- Net fiat proceeds.
- Exchange fiat account statement.
- Withdrawal request.
- Withdrawal status.
- Payment reference.
- Exact legal sender name.
If a banking partner sends the payment rather than the exchange itself, include the exchange’s explanation and a reference connecting the payment to your withdrawal.
This is a common failure point.
The customer expects a wire from “Example Exchange,” but the bank receives money from an unfamiliar payments company. Without prior disclosure, that can look like an unexplained third-party transfer.
Step 6: Reconcile the Tax File
A bank is not conducting a tax audit, but unexplained tax inconsistencies can undermine the entire account of the funds.
The following should align:
- Acquisition dates.
- Quantities acquired.
- Cost basis.
- Disposals.
- Mining, staking, compensation, or airdrop income.
- Exchange proceeds.
- Claimed holding period.
- Legal owner.
- Tax residence.
- Capital-gain or ordinary-income classification.
- Information reports received from brokers or exchanges.
For U.S. taxpayers, digital assets are generally treated as property. The IRS guidance on digital-asset taxes and recordkeeping explains the need to report relevant activity and maintain records supporting the tax treatment.
Form 1099-DA gross-proceeds reporting began for covered broker transactions effected on or after January 1, 2025, with the first related statements generally furnished in 2026.
Basis reporting applies to certain covered digital assets for sales effected on or after January 1, 2026. The Form 1099-DA reporting instructions distinguish covered and noncovered assets and explain the reporting requirements.
That distinction is particularly important for assets transferred into an exchange from self-custody. A broker’s form may not include a reliable acquisition history or report basis for those transferred-in assets.
A missing basis figure does not establish that the investor’s actual basis is zero. It means the investor still needs supporting records.
Include, as applicable:
- Filed tax returns.
- Form 8949 and Schedule D.
- Forms 1099-DA or substitute broker statements.
- Business schedules for mining, trading, or token compensation.
- Foreign asset or account disclosures where applicable.
- Cost-basis reports.
- An accountant-prepared reconciliation.
- Estimated tax calculations for the current-year sale.
- Evidence of estimated tax payments, if already made and relevant.
If the sale happened in the current tax year and the filing deadline has not arrived, say so.
Provide a draft gain or income calculation and, where appropriate, a tax adviser’s letter explaining the intended treatment.
Do not backdate tax records or claim that a transaction has already been reported when it has not.
Use an Evidence-Quality Hierarchy
The strongest compliance packages use customer-created summaries to organize evidence, not to replace independent records.
Not every document carries the same weight. I would organize the file around the following practical hierarchy.
Tier 1: Independent or Official Primary Records
- Bank statements.
- Official exchange statements.
- Wire records.
- Filed tax returns and information reports.
- Signed legal agreements.
- Audited financial statements.
- Probate or inheritance documents.
- Court or government documents.
- Employer compensation records.
These records still need to be relevant and authentic. A filed tax return shows what was reported; it does not independently prove every underlying acquisition or establish that all funds are lawful.
Tier 2: Independently Verifiable Technical Evidence
- Public blockchain records.
- Cryptographic wallet signatures.
- Exchange-generated transaction hashes.
- Independent blockchain forensic reports.
- Custodian confirmations.
- Multisignature configuration records.
Technical evidence also has limits. A blockchain record can establish that a transaction occurred without identifying the legal owner of the address.
Tier 3: Contemporaneous Supporting Evidence
- Emails.
- Invoices.
- Hardware purchase receipts.
- Protocol statements.
- Mining-pool records.
- Screenshots captured at the time.
- Accounting workpapers.
Tier 4: Customer-Prepared Evidence
- Personal spreadsheets.
- Written declarations.
- Reconstructed timelines.
- Portfolio snapshots.
- Unverified tax-software reports.
Tier 4 material is useful for navigation, explanation, and reconciliation. It should point to stronger supporting evidence wherever possible.
A polished spreadsheet is not independent proof of the facts entered into it.
5. Proving Source of Wealth for Complex Crypto Histories
The right source-of-wealth evidence depends on how the initial capital or digital assets were actually acquired.
A salary-funded Bitcoin purchase, an early mining operation, a token grant, and a crypto-backed loan are different economic events. I would not force them into the same explanation.
| Source of wealth or funding | Evidence to collect | Likely compliance concern |
|---|---|---|
| Salary and personal savings | Employment records, pay statements, Forms W-2, tax returns, and bank statements | Whether the investment size was plausible against documented income |
| Business income | Company accounts, distributions, tax returns, invoices, and bank statements | Whether the money belonged to the individual or the business |
| Business sale | Sale agreement, closing statement, capitalization table, bank receipt, and tax records | Ownership of the interest sold and actual receipt of proceeds |
| Inheritance | Will, probate documents, estate account, executor letter, distribution statement, and transfer records | Identity of the estate, beneficiary status, and asset valuation |
| Gift | Gift agreement, donor transfer, applicable tax forms, and donor source-of-wealth evidence where required | Whether the donor legitimately owned the assets and the gift was genuine |
| Mining | Hardware invoices, pool records, wallet payouts, electricity costs, business accounts, and tax returns | Whether claimed production was plausible and properly reported |
| Staking or validation | Validator records, staking-contract interactions, reward records, wallet records, and tax treatment | Whether rewards can be distinguished from third-party deposits |
| Token compensation | Employment or advisory agreement, token grant, vesting schedule, capitalization table, compensation records, and tax returns | Whether the tokens were compensation, an investment, or an issuer allocation |
| SAFT or private token sale | Signed agreement, subscription payment, wallet allocation, vesting records, and issuer confirmation | Beneficial ownership, securities-law issues, and token provenance |
| Trading profits | Complete exchange histories, wallet records, cost basis, and tax reports | Whether profits reconcile across platforms |
| Crypto-backed loan | Loan agreement, collateral wallet, lender identity, disbursement records, and repayment terms | Whether the incoming payment is debt rather than sale proceeds and whether the lender is credible |
| OTC or peer-to-peer purchase | Counterparty identity, agreement, invoice, bank settlement, communications, and transaction hash | Unknown counterparties, cash settlement, third-party payments, or unlicensed activity |
| DAO compensation | Contributor agreement, governance proposal, multisignature payment, vesting, and tax records | Who authorized the payment and whether the individual or an entity earned it |
| Airdrop or protocol distribution | Eligibility criteria, claim transaction, wallet ownership evidence, valuation, and tax treatment | Whether the distribution was legitimate and correctly classified |
A SAFT is a Simple Agreement for Future Tokens. If one is part of the history, the agreement and funding records need to connect to the actual token allocation.
A crypto-backed loan also needs careful wording. Borrowed funds are not automatically sale proceeds, investment gains, or earned income. The compliance explanation should describe the real transaction.
Early Purchases With Missing Exchange Records
A defunct exchange or inaccessible account does not make proof impossible. It does make corroboration more important.
Collect:
- Historical bank transfers to the exchange.
- Archived account emails.
- Trade and withdrawal notifications.
- API data backups.
- Contemporaneous tax workpapers.
- On-chain withdrawals from known exchange clusters.
- Bankruptcy or creditor-claim records.
- Old device backups, without including private keys in the bank submission.
- Portfolio statements created at the time.
- Professional forensic reconstruction.
A personal declaration should explain why the records are missing.
It should not be the only evidence that the acquisition happened.
Early Mining
An early miner should not rely on “I mined it myself” as the entire explanation.
A stronger file shows:
- Hardware purchases.
- Approximate hash rate.
- Mining-pool participation.
- Pool payout addresses.
- Coinbase transactions creating block rewards, or mining-pool distributions.
- Electricity or hosting costs.
- Business registration, if applicable.
- Historical wallet balances.
- Tax or accounting treatment.
- Subsequent wallet transfers.
Here, “coinbase transaction” means the technical blockchain transaction that creates a block reward, not a transaction on the Coinbase exchange.
The claimed production should be technically plausible against the equipment, network conditions, and relevant period.
Gifts and Inheritances
The recipient’s own source-of-wealth file may not be enough. The bank may ask how the donor or estate acquired the assets.
For a gift, prepare:
- Donor identity.
- Relationship to the recipient.
- Gift letter or agreement.
- Donor wallet and transfer transaction.
- Evidence of the donor’s acquisition.
- Applicable gift-tax filings.
- A statement that the gift is unconditional, if that is true.
For an inheritance, prepare:
- Will or trust instrument.
- Probate documentation.
- Executor or trustee confirmation.
- Valuation at the relevant date.
- Estate wallet or custodian records.
- Distribution transaction.
- Cost basis and tax treatment.
I would be particularly careful to distinguish the date the deceased person acquired the assets, the relevant estate valuation date, and the date of distribution. Those dates serve different purposes.
Companies, Trusts, Funds, and Family Offices
When an entity receives the proceeds, the bank needs to understand both the assets and the ownership structure.
The FFIEC guidance on domestic and foreign business entities helps explain why banks examine ownership, control, business purpose, and the source of funds or wealth when assessing entity relationships.
Include:
- Formation documents.
- Beneficial ownership chart.
- Operating agreement, partnership agreement, or trust instrument.
- Authorized signer list.
- Board or manager resolution authorizing the liquidation.
- Financial statements.
- Tax returns.
- Capital-contribution records.
- Asset ownership ledger.
- Investment or treasury policy.
- Evidence explaining how the entity acquired the crypto assets.
Do not move personally owned crypto into a company exchange account immediately before the sale without documenting the contribution or transfer.
That creates ownership, accounting, tax, and compliance questions at the same time.
6. What to Do When a Bank Rejects or Holds a Crypto-Related Transfer
When a crypto-related payment is delayed or rejected, first establish what happened and where the money is. Do not immediately create a new transfer route.
The first 24 hours matter. My priorities would be to stabilize the facts, preserve records, and avoid creating additional alerts.
Step 1: Classify the Event
Determine whether the problem is:
- An exchange withdrawal restriction.
- A pending fiat withdrawal.
- A sending-bank rejection.
- An intermediary-bank rejection.
- A beneficiary-bank hold.
- An account-wide restriction.
- An account closure.
- A sanctions block.
- A law-enforcement restriction.
Do not use “frozen” and “rejected” interchangeably when speaking with institutions.
A returned payment and legally blocked property require very different responses.
Step 2: Stop Creating Workaround Transactions
Until the reason is clear:
- Do not send duplicate wires.
- Do not retry through another exchange.
- Do not route the money to a friend or relative.
- Do not divide the amount among banks.
- Do not move the crypto through additional wallets to work around the review.
- Do not delete or alter account information.
- Do not contact employees through social media.
- Do not give different explanations to different departments.
Repeated attempts can turn a single transaction review into an investigation of a broader pattern.
If a genuinely urgent operational issue exists, address it through the institution and appropriate advisers rather than improvising a workaround.
Step 3: Obtain Case and Payment Identifiers
Request:
- Bank case number.
- Exchange support-ticket number.
- Withdrawal ID.
- Wire reference.
- Fedwire IMAD or OMAD, where applicable.
- SWIFT UETR and relevant payment-message details, where applicable.
- ACH trace number, where applicable.
- Date, amount, currency, sender, and beneficiary.
- Return or rejection reason, if available.
For SWIFT payments, the supporting confirmation may involve an ISO 20022 payment message, such as pacs.008, or an MT103 where relevant to the payment and available records. Do not assume every current international payment will be documented in the older MT103 format.
The sender should generally initiate the formal payment trace because it usually has the contractual relationship with the sending bank.
If the exchange’s banking partner sent the wire, the exchange may need to arrange that investigation.
Step 4: Ask Precise Questions
Ask:
- Is the payment pending, rejected, returned, or legally blocked?
- Which institution currently controls the funds?
- Does the issue concern identity, account ownership, sender identity, payment purpose, documentation, fraud, or sanctions?
- Which exact documents are required?
- What is the submission deadline?
- Which secure channel should I use?
- Does my customer profile or expected account activity need updating?
- If the wire was returned, what information must change before it is resent?
Do not ask whether the bank filed a suspicious activity report, or SAR.
Banks generally cannot disclose a SAR or information that would reveal its existence.
In their September 2, 2026, clarification on SAR confidentiality and customer communications, FinCEN and the federal banking agencies explained that SAR confidentiality does not prevent banks from discussing underlying transactions, requesting source-of-funds documentation, explaining that a delay or restriction may relate to suspected fraud or suspicious activity, or communicating an account-closure decision, provided they do not reveal the existence of a SAR.
That statement clarified existing requirements. It did not create a right to receive the institution’s internal alert logic or require disclosure of a SAR.
There is still a practical difference between “the bank cannot discuss a SAR” and “the bank cannot ask for documents or discuss the underlying payment.”
Step 5: Submit One Consolidated Response
Avoid sending 30 separate emails with unexplained attachments.
Use:
- A short cover letter.
- A request-by-request response matrix.
- The executive summary.
- A document index.
- Supporting exhibits.
An illustrative response matrix might look like this:
| Bank request | Response | Supporting file |
|---|---|---|
| Explain the incoming USD 1.8 million | Proceeds from the sale of 22 BTC on the specified date | Executive summary, section 2 |
| Prove the source of the original investment capital | Funded from salary savings and business-sale proceeds | Files 02.01 through 02.08 |
| Prove wallet control | Signed-message verification and exchange withdrawal history | Files 05.01 and 05.02 |
| Explain bridge use | Assets moved from Ethereum to Arbitrum for a documented DeFi position | Files 06.14 through 06.19 |
| Identify the wire sender | The exchange uses a named regulated payment partner | Files 07.06 and 07.07 |
| Provide tax documentation | Cost-basis report and tax-adviser reconciliation | Files 08.01 through 08.05 |
Answer the exact question asked.
Do not bury the key fact in a 500-page attachment and expect the analyst to find it.
Step 6: Preserve the Current State of Every Account
Export records immediately because account interfaces, labels, and downloadable histories can change.
Preserve:
- Exchange statements.
- Original CSV files.
- Account profile and verification status.
- Deposit and withdrawal history.
- Trade confirmations.
- Wallet balances.
- Transaction hashes.
- Bank messages.
- Secure-chat transcripts.
- Payment records.
- Case numbers.
- Terms and policies in effect during the relevant period.
Record timestamps and create a file manifest.
I would keep an untouched copy of every original export and work from duplicates when preparing the response.
Step 7: Escalate in the Right Order
A reasonable escalation sequence is:
- Basic payments support or exchange support.
- Fraud operations or payment investigations.
- Relationship manager or private banker.
- The formal compliance-document submission channel.
- Internal complaints or executive-resolution team.
- Qualified banking, sanctions, or financial-crime counsel.
- The appropriate regulator or consumer-complaint channel after identifying the institution’s charter, license, and jurisdiction.
Legal counsel should be involved early if:
- OFAC or another sanctions authority may be involved.
- Law enforcement has issued a restraint or seizure order.
- The institution requests an explanation concerning potentially criminal activity.
- Material funds remain unavailable for an extended period.
- The transaction involves sanctioned jurisdictions or counterparties.
- The institution is closing a complex business, trust, or fiduciary relationship.
- Earlier statements may have been incomplete or inaccurate.
Do not threaten regulatory complaints during the first routine document request.
First build a clear record showing that you responded promptly, completely, and consistently. A complaint is not a mechanism for overriding a valid legal restriction.
7. Stress-Test Your Crypto Cash-Out File Before Sending the Money
A defensible file should survive a skeptical review by someone who knows nothing about your history.
Before initiating the transfer, I would challenge the package using the following questions.
The goal is not to create the appearance of certainty. It is to identify gaps while there is still time to explain or resolve them.
Identity and Ownership
- Do the wallet, exchange, OTC account, entity, and bank-account ownership records align?
- If not, is every ownership transfer documented?
- Are beneficial owners and authorized signers identified?
- Can wallet control be independently demonstrated?
- Are trust, company, fund, and family-office relationships clear?
Source of Wealth
- Is the source of the initial capital identified?
- Is the amount plausible against income or prior wealth?
- Are salary, business, inheritance, mining, gift, or allocation records included?
- If another person supplied the wealth, is that person’s source documented where required?
- Are gaps explained rather than ignored?
Source of Funds
- Can the specific assets sold be traced to the customer?
- Does the exchange deposit match the blockchain transaction?
- Does the trade confirmation match the fiat balance?
- Do fees explain the difference between gross and net proceeds?
- Does the withdrawal record match the incoming bank payment?
- Is the actual sender identified?
On-Chain History
- Is every material wallet listed?
- Are internal transfers labeled?
- Are DEX swaps and bridge transactions mapped?
- Are staking, mining, liquidity provision, lending, and airdrops recorded?
- Has material direct and indirect high-risk exposure been assessed?
- Have sanctions and mixer connections been addressed?
- Have unsolicited dust and spam transactions been identified?
Banking Route
- Was the bank notified before the transfer was initiated?
- Was the expected sender disclosed?
- Does the amount fit the updated customer profile?
- Are installment payments explained?
- Does the receiving account fit the beneficial ownership and transaction purpose?
- Is a secure document-submission channel available?
- If a test payment is used, is it approved where practical or clearly identified?
Tax and Accounting
- Do acquisition dates and quantities match the records?
- Is the cost-basis method consistent with the tax file?
- Are income-producing events included?
- Does entity ownership match the taxpayer reporting the transaction?
- Are current-year estimates clearly separated from filed returns?
- Has a tax professional reviewed material inconsistencies?
Presentation and Data Security
- Can the reviewer understand the transaction in three minutes?
- Does every material statement in the summary point to supporting evidence?
- Are original records preserved?
- Are redactions limited and clearly marked?
- Are filenames chronological and descriptive?
- Are seed phrases and private keys excluded?
- Is the package being delivered only through an approved secure channel?
What a Defensible Crypto Cash-Out Looks Like
A defensible crypto cash-out tells one consistent economic story across ownership records, blockchain activity, exchange statements, bank payments, and tax documents.
The clearest substantial cash-outs usually follow this pattern:
- Lawful wealth funded the initial investment.
- The investment entered crypto through a documented route.
- The assets remained under identifiable ownership.
- Every material on-chain movement can be explained.
- The assets reached a regulated cash-out provider.
- The sale generated clearly identified fiat proceeds.
- A previously disclosed sender transmitted the fiat payment.
- The receiving bank was notified in advance.
- Tax and accounting records tell the same story.
- Exceptions were disclosed before the reviewer discovered them.
Compliance does not need your history to be simple. It needs your history to be understandable and verifiable.
A Web3-native investor may have used dozens of wallets, protocols, bridges, exchanges, validators, and smart contracts. That complexity can still be acceptable to a bank if it is converted into a chronological, ownership-consistent, reconciled record.
When I compare traditional banking with crypto, this is where the two systems meet. The blockchain can show that transactions occurred. The banking file must explain who owned the assets, why the transactions occurred, and how the resulting payment belongs to the customer.
The cash-out barrier is rarely solved by finding a hidden threshold or inventing a more creative transfer route.
It is solved by reducing uncertainty before the payment reaches the bank.
Sponsored Partner: Volet.com
Looking for a simple, everyday way to buy, hold, and sell cryptocurrencies alongside your traditional currencies and payment cards?
- Read my full breakdown: Complete Volet Review on DoraMilen.com
- Get started right away: Open your free Volet account using my referral link