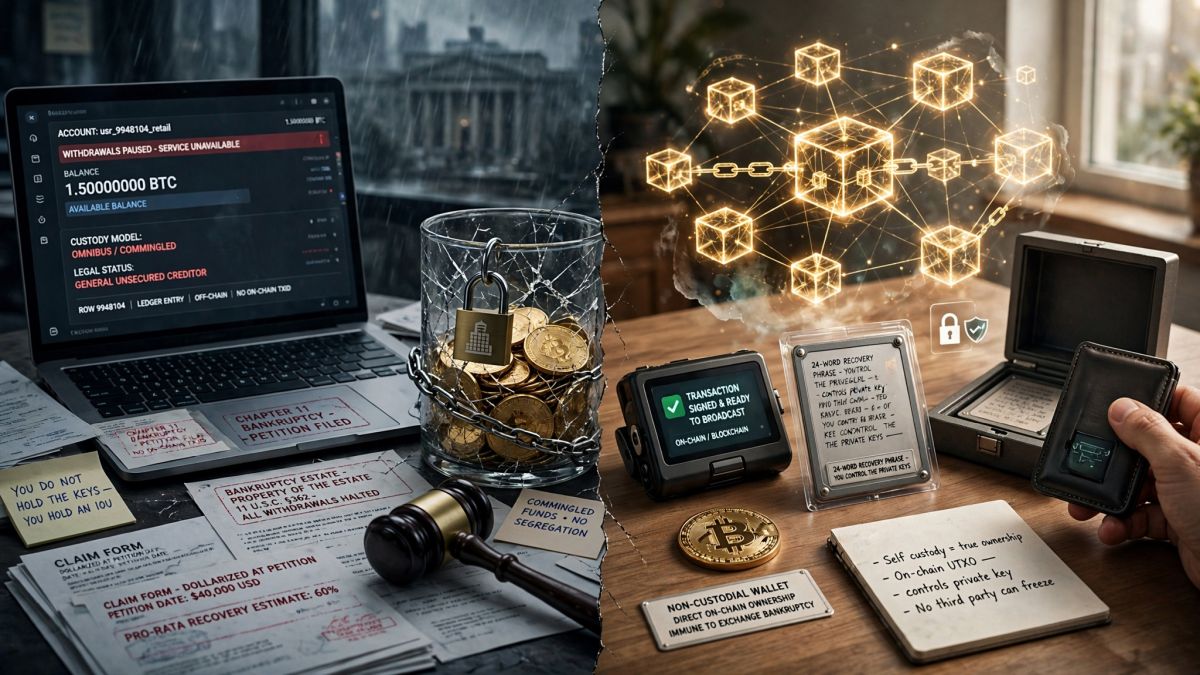
When you log into a centralized cryptocurrency exchange like Coinbase, Kraken, or Robinhood and see “1.5 BTC” sitting in your portfolio, you are not looking at Bitcoin on a blockchain. You are looking at an internal database entry, essentially an IOU, showing that the platform owes you 1.5 BTC.
During my 25 years in traditional banking, I spent thousands of hours reviewing clearinghouse settlement frameworks, commercial custody agreements, and balance sheet liability structures. The biggest shock for everyday investors transitioning from traditional banking to crypto is discovering that user interface design hides legal reality. A sleek mobile app makes buying Bitcoin feel identical to buying shares of Apple through a registered stockbroker or depositing paychecks into a checking account. Beneath the surface, however, the property rights governing your funds are completely different.
If a centralized crypto platform freezes withdrawals and files for Chapter 11 bankruptcy protection, whether you recover 100 percent of your assets or wait five years to receive pennies on the dollar comes down to one legal and technical distinction: custodial versus non-custodial architecture, and whether a bankruptcy judge classifies you as the legal owner of segregated property or as a general unsecured creditor.
Do You Own Your Bitcoin on an Exchange? The Legal and Technical Reality
No, when you hold cryptocurrency in a standard retail account on a centralized exchange, you do not hold direct cryptographic ownership of those coins on the blockchain; instead, the exchange holds the private keys in omnibus wallets while assigning you a contractual claim on its internal ledger.
To understand why this distinction matters in a courtroom, we have to look at how a centralized exchange actually processes deposits and trades under the hood. When you deposit Bitcoin to a custodial exchange, the platform generates a deposit address for you. Once your transaction confirms on-chain, the exchange’s automated treasury system routinely sweeps those funds out of that deposit address and consolidates them into massive, pooled wallets known as omnibus wallets (split between internet-connected “hot” wallets for daily liquidity and offline “cold” storage vaults).
From that moment forward, your trading activity on the exchange does not touch the Bitcoin blockchain. If you sell 0.5 BTC for USD or swap it for ETH on the platform, no blockchain transaction occurs. Instead, the exchange updates rows in its private relational database (such as PostgreSQL or Oracle). Look at the difference between what the exchange database records and what the Bitcoin blockchain actually recognizes:
// 1. What the Custodial Exchange's Internal SQL Database Shows (Off-Chain IOU)
{
  "account_id": "usr_9948104_retail",
  "kyc_status": "VERIFIED",
  "ledger_entries": [
    {
      "asset": "BTC",
      "available_balance": "1.50000000",
      "locked_in_orders": "0.00000000",
      "custody_model": "OMNIBUS_COMMINGLED",
      "on_chain_txid": null
    }
  ]
}
Compare that internal database entry with an actual Unspent Transaction Output (UTXO) queried directly from a Bitcoin Core node via bitcoin-cli gettxout:
// 2. What the Bitcoin Protocol Actually Recognizes (On-Chain UTXO Ownership)
{
  "bestblock": "000000000000000000018a9c4d7e3f1b2a5c8d9e0f1a2b3c4d5e6f7a8b9c0d1e",
  "confirmations": 1420,
  "value": 1.50000000,
  "scriptPubKey": {
    "asm": "0 8f3a2b1c4d5e6f7a8b9c0d1e2f3a4b5c6d7e8f9a",
    "desc": "wpkh([d34db33f/84'/0'/0'/0/0]0279be667ef9dcbbac55a06295ce870b07029bfcdb2dce28d959f2815b16f81798)#x8k2m9p1",
    "hex": "00148f3a2b1c4d5e6f7a8b9c0d1e2f3a4b5c6d7e8f9a",
    "address": "bc1q3uazk8zdtehh4z6up502s36tt4ha0u6s7239r",
    "type": "witness_v0_keyhash"
  },
  "coinbase": false
}
In the second snippet, whoever controls the private key corresponding to the public key hash (8f3a2b...) has the unilateral mathematical authority to construct a valid cryptographic signature and spend that 1.5 BTC. In a custodial exchange, the company’s key-management infrastructure holds that private key. As highlighted in Fortune’s coverage of Coinbase’s custodial bankruptcy warning, the exchange holds the private keys and lets you access your account with a conventional password, meaning the company ultimately governs whether you can access those assets.
When funds sit in an omnibus wallet, your coins are commingled with the coins of millions of other retail users. As noted in DAG Wealth’s institutional guide to crypto insurance and omnibus custody, retail exchange holdings typically sit in commingled omnibus wallets rather than bankruptcy-remote, individually segregated on-chain accounts. In traditional finance, commingling client assets without statutory trust protections is a massive red flag because once fungible assets are mixed together and the custodian becomes insolvent, tracing individual property ownership becomes a legal nightmare.
Traditional Bank Deposits vs. Crypto Exchanges: FDIC, SIPC, and the Illusion of Safety
Traditional bank accounts and registered brokerage accounts protect retail customers through statutory government-backed frameworks (FDIC and SIPC) and strict segregation laws, whereas cryptocurrency held on an exchange enjoys zero federal deposit insurance and relies entirely on private contract law.
Here is something that surprises even seasoned investors when I explain how commercial banking works: when you deposit 50,000 USD into a traditional checking account at JPMorgan Chase or Bank of America, you do not legally “own” physical cash sitting in a vault with your name on it. Under centuries of Anglo-American banking law, a standard bank deposit creates a debtor-creditor relationship. You are lending your money to the bank, the bank records your deposit as a liability on its balance sheet, and the bank uses that cash to issue mortgages and commercial loans.
If a bank Deposit is legally a loan to the bank, why don’t everyday depositors panic about becoming unsecured creditors? Because after the bank runs of the Great Depression, Congress built a strict statutory firewall around traditional finance:
- FDIC Insurance for Bank Deposits: If an FDIC-insured bank fails, it does not enter the corporate Chapter 11 Bankruptcy Code. Instead, it enters a specialized FDIC receivership process. The Federal Deposit Insurance Corporation guarantees dollar deposits up to 250,000 USD per depositor, per insured bank, for each account ownership category, typically restoring access to insured funds within days.
- SIPC Protection and SEC Rule 15c3-3 for Brokerages: When you buy stocks or bonds through a traditional broker-dealer like Fidelity or Charles Schwab, SEC Rule 15c3-3 (the Customer Protection Rule) legally mandates that the broker segregate customer securities from the firm’s proprietary assets. If a member brokerage collapses and customer assets are missing, the Securities Investor Protection Corporation (SIPC) steps in to restore securities and cash up to 500,000 USD (including up to 250,000 USD for cash claims).
Now contrast that with a cryptocurrency exchange. As detailed in Nixon Peabody’s legal analysis of cryptocurrency exchange bankruptcies, cryptocurrency accounts on exchanges are not like traditional brokerage accounts protected by SIPC and are not FDIC insured. Even if an exchange partners with an FDIC-insured bank to hold your resting U.S. dollar balances, that coverage only protects fiat USD held at the bank should the bank itself fail; it never covers Bitcoin, Ether, or stablecoins. Following deceptive marketing claims by failed platforms like Voyager Digital, regulators tightened enforcement: according to Spark’s documentation on custodial risk and the 2026 FDIC labeling rule, U.S. platforms partnered with banks are strictly required to clearly label cryptocurrency balances as “Non-Deposit Products.”
Furthermore, as tracked in Eco’s 2026 comparison of custodial and non-custodial wallet tradeoffs, platforms like Robinhood Crypto explicitly state in their agreements that cryptocurrencies held in user accounts are neither protected by SIPC nor covered by FDIC insurance, and while exchanges like Coinbase carry private crime insurance for hot wallet thefts, those private policies contain strict dollar limits and exclusions that do not protect users against corporate insolvency.
| Feature | Commercial Bank (Checking/Savings) | Registered Broker-Dealer (Equities/ETFs) | Retail Crypto Exchange (Custodial Account) | Non-Custodial Wallet (Hardware/Self-Custody) |
|---|---|---|---|---|
| Legal Relationship | Debtor-Creditor (You lend fiat to the bank) | Custodial Bailment / Street Name Trust | Governed by Terms of Service (Bailment vs Debtor-Creditor) | Direct Cryptographic Possession (No Intermediary) |
| Statutory Insurance | FDIC Insured up to 250,000 USD per depositor | SIPC Protected up to 500,000 USD (250,000 USD cash) | Zero FDIC or SIPC coverage on crypto assets | None (User bears 100 percent of key security responsibility) |
| Asset Segregation | Commingled on bank balance sheet (Fractional Reserve) | Legally segregated from firm assets under SEC Rule 15c3-3 | Frequently commingled in omnibus hot and cold wallets | Strictly isolated on-chain at user-controlled addresses |
| Insolvency Regime | FDIC Receivership (Federal Deposit Insurance Act) | SIPA Liquidation (Fast-track return of customer securities) | U.S. Bankruptcy Code Chapter 11 or Chapter 7 | Immune to third-party corporate bankruptcy |
| Typical Resolution Time | 1 to 3 business days | Weeks to a few months for street-name transfers | 2 to 10+ years of bankruptcy court litigation | Immediate (No third party can freeze on-chain signing) |
Demystifying the “General Unsecured Creditor”: What Happens When an Exchange Liquidates
When a custodial crypto platform files for bankruptcy and the court rules that user deposits belong to the bankruptcy estate, customers lose title to their coins and become general unsecured creditors who stand near the very back of the line to receive a fraction of their account’s petition-date dollar value.
In my banking career, whenever a corporate borrower began showing signs of distress, our credit risk committee immediately checked one thing: are we secured with perfected first-lien collateral, or are we unsecured? In bankruptcy law, being a general unsecured creditor is the financial equivalent of holding an unbacked promise at the back of a very long line.
When a cryptocurrency exchange or lender files a voluntary petition under Chapter 11 (reorganization) or Chapter 7 (liquidation) of the U.S. Bankruptcy Code, two legal mechanisms trigger at the exact second of the filing:
- The Automatic Stay (11 U.S.C. Section 362): As explained in Freeman Law’s legal overview of custodial wallets and the automatic stay, filing a bankruptcy petition immediately activates the automatic stay, a federal court injunction that halts all customer withdrawals, account transfers, and individual lawsuits against the company.
- Creation of the Bankruptcy Estate (11 U.S.C. Section 541): All legal or equitable interests of the debtor in property as of the commencement of the case are swept into the “bankruptcy estate.”
The Step-by-Step Lifecycle of a Crypto Exchange Bankruptcy
To visualize how your money moves through the legal system when an exchange collapses, follow this seven-stage insolvency lifecycle:
STAGE 1: LIQUIDITY CRISIS & WITHDRAWAL FREEZE
The exchange suffers a balance sheet hole (from bad loans, hacks, or commingled trading losses).
Management halts all off-platform crypto withdrawals citing "extreme market conditions."
   |
   v
STAGE 2: CHAPTER 11 PETITION & AUTOMATIC STAY (11 U.S.C. Sec. 362)
The company files for bankruptcy protection. The Automatic Stay legally locks all omnibus wallets.
The exact date and timestamp of the filing becomes the "Petition Date."
   |
   v
STAGE 3: PROPERTY OF THE ESTATE LITIGATION (11 U.S.C. Sec. 541)
The bankruptcy judge examines the platform's Terms of Service and wallet segregation:
  -> Path A (True Custodial Bailment / Segregated Trust): Assets are excluded from the estate
     and eventually returned in-kind to users after identity and solvency verification.
  -> Path B (Title Transferred / Commingled Omnibus Estate Property): Assets belong to the
     company's bankruptcy estate. Users are classified as General Unsecured Creditors.
   |
   v
STAGE 4: DOLLARIZATION OF CLAIMS (11 U.S.C. Sec. 502(b))
All user crypto claims in Path B are converted into fixed USD amounts based on the spot price
of the cryptocurrency on the exact Petition Date, stripping users of future crypto price upside.
   |
   v
STAGE 5: THE ABSOLUTE PRIORITY WATERFALL
Estate assets are liquidated or restructured to pay claims in strict statutory order:
  1. Secured Creditors (Institutional lenders holding perfected liens)
  2. Administrative Expenses (Bankruptcy attorneys, restructuring advisors, forensic auditors)
  3. Priority Unsecured Claims (Unpaid taxes, limited employee wages)
  4. General Unsecured Creditors (Retail exchange customers share remaining funds pro-rata)
  5. Equity Holders (Shareholders receive nothing unless all creditors are paid 100% plus interest)
   |
   v
STAGE 6: PREFERENCE CLAWBACKS (11 U.S.C. Sec. 547)
The estate sues customers who successfully withdrew funds during the 90 days prior to the
Petition Date, demanding they return "preferential transfers" to the estate pool.
   |
   v
STAGE 7: PLAN CONFIRMATION & PRO-RATA DISTRIBUTION
Years after the freeze, the court confirms a Chapter 11 plan and distributes remaining cash
or liquid tokens pro-rata to unsecured creditors.
Why “Dollarization” Hurts Crypto Creditors Even When Recoveries Look High
One of the most painful mechanics of U.S. bankruptcy law is claim dollarization under Section 502(b) of the Bankruptcy Code. Because crypto exchanges almost always collapse at the bottom of a brutal bear market, the court values your claim in U.S. dollars at the moment the bankruptcy petition is filed.
As noted in the American Bankruptcy Institute’s guide to cryptocurrency in bankruptcy, the volatility of cryptocurrency creates massive friction during plan confirmation, and general unsecured creditors only get paid after administrative, priority, and secured creditors are satisfied in full. Let’s walk through the exact math of how dollarization and administrative burn impact a retail user holding 2 BTC on a failed platform:
BANKRUPTCY CLAIM & RECOVERY CALCULATION EXAMPLE

User Account Balance at Freeze:          2.00000000 BTC
BTC Spot Price on Petition Date:         20,000 USD per BTC
-------------------------------------------------------------------------
Allowed Unsecured Claim (Dollarized):    2.0 BTC * 20,000 USD = 40,000 USD

--- Fast Forward 3 Years to Plan Distribution ---
Total Estate Assets Available:           1,800,000,000 USD
Less Secured Creditor Claims:            - 300,000,000 USD
Less Chapter 11 Legal/Admin Fees:        - 250,000,000 USD
Less Priority Tax/Wage Claims:           -  50,000,000 USD
-------------------------------------------------------------------------
Net Distributable Pool for Unsecured:    1,200,000,000 USD
Total Allowed Unsecured Claims Pool:     2,000,000,000 USD

Pro-Rata Recovery Rate:                  1,200,000,000 / 2,000,000,000 = 60%
User Cash Payout (60% of 40,000 USD):    24,000 USD

--- Real Purchasing Power Impact if BTC Rose to 80,000 USD ---
Value of 2.0 BTC at Distribution Date:   160,000 USD
Actual BTC Equivalent Recovered:         24,000 USD / 80,000 USD = 0.30 BTC (15% In-Kind)
Notice the trap here. The bankruptcy attorneys will issue press releases celebrating that unsecured creditors recovered “60 percent of their allowed claims!” Yet if Bitcoin rose from 20,000 USD on the petition date to 80,000 USD by the time checks are mailed out three years later, your 24,000 USD payout only buys back 0.30 BTC. In real crypto terms, you lost 85 percent of your Bitcoin stack while the estate paid hundreds of millions of dollars in legal and advisory fees. Furthermore, as explained in TaxBit’s guide to tax loss deductions for unsecured crypto creditors, affected customers cannot even claim a tax deduction for their bankruptcy losses until the final recovery amount is determined with reasonable certainty, leaving funds and tax write-offs in limbo for years.
Case Study: How Terms of Service Turned Celsius Users into Unsecured Lenders
The landmark January 2023 bankruptcy ruling in the Celsius Network case proved that unambiguous clickwrap Terms of Service transferring title of deposited crypto to the platform legally strip customers of ownership and empower the bankrupt company to sell user tokens to pay its own legal bills.
Whenever readers ask me whether bankruptcy courts actually enforce those 40-page “Terms of Use” agreements that everyone scrolls past and clicks “Accept” on, I point them directly to Judge Martin Glenn’s 45-page Memorandum Opinion in the Celsius case, issued on January 4, 2023, in the U.S. Bankruptcy Court for the Southern District of New York.
Before filing for Chapter 11 bankruptcy in July 2022, Celsius Network marketed itself as a safe alternative to traditional banks, promising up to 18 percent annual yield on deposited tokens. As detailed in TechCrunch’s analysis of Celsius’s 4.2 billion USD Earn program, roughly 600,000 customer accounts held 4.2 billion USD worth of digital assets in Celsius’s flagship “Earn” accounts when withdrawals were frozen.
When Celsius ran out of operating cash during the bankruptcy proceedings, the company asked the court for permission to sell 18 million USD worth of customer-deposited stablecoins to pay its Chapter 11 administrative and legal expenses. Thousands of shocked customers objected, arguing that they had merely “loaned” their coins to Celsius and still owned them.
Judge Glenn distilled the entire dispute down to fundamental contract law:
- Enforceability of Clickwrap Contracts: As summarized in Crowell FinTalk’s review of Celsius account holder acceptance rates, 99.86 percent of Celsius account holders clicked “Accept” on the updated Terms of Use, which the court ruled constituted a binding, enforceable contract.
- Unambiguous Transfer of Title: Version 8 of the Celsius Terms of Use explicitly stated that in exchange for earning yield, the user granted Celsius “all right and title to such Eligible Digital Assets, including ownership rights,” and authorized Celsius to pledge, rehypothecate, sell, and commingle those assets without holding them in trust.
- Rejection of the “Lending” Defense: As noted in Sidley Austin’s legal briefing on the Celsius bankruptcy ruling, customers argued that because the Terms of Use used the words “loan” and “lending,” users retained ownership. Judge Glenn rejected this, noting that in financial law, it is entirely standard for a party lending assets to a debtor to hold only an unsecured creditor claim in bankruptcy.
The immediate consequence was brutal. As reported in Decrypt’s report on the court authorizing Celsius to sell customer stablecoins, Judge Glenn ruled that the Earn assets belonged to the bankruptcy estate and authorized Celsius to sell the 18 million USD in stablecoins to fund the administration of the bankruptcy case itself. In other words, customers’ own stablecoins were liquidated to pay the lawyers arguing against them. Later that year, as covered in Restructuring GlobalView’s examination of retail borrower collateral ownership, the court reached the exact same conclusion regarding retail borrowers who posted crypto collateral for cash loans: the fine print transferred ownership of the collateral to the estate.
Even users who did not use yield accounts faced harrowing legal battles. As explained in Harvard Law School’s Bankruptcy Roundtable analysis of Celsius Network, Celsius offered separate “Custody” accounts whose Terms of Use stated that title remained with the user, yet the unsecured creditors’ committee argued that only assets actually sitting in segregated Custody wallets (and not commingled or transferred shortly before bankruptcy) could be excluded from the estate. Worse still, as highlighted in Bracewell LLP’s breakdown of the Celsius Earn account decision, the court moved into a second phase of litigation addressing 90-day preference claims, exposing everyday users who withdrew their own funds within 90 days before the bankruptcy filing to clawback demands.
The Coinbase 10-Q Disclosure and the SAB 121 Accounting Shift
Even when a regulated exchange does not lend out your coins and removes customer crypto from its corporate balance sheet, the legal question of whether custodied retail crypto becomes bankruptcy estate property remains untested in federal court.
After seeing lenders like Celsius and BlockFi collapse, many investors assumed that sticking to a non-lending, publicly traded U.S. exchange like Coinbase eliminated this legal ambiguity. Then came May 2022.
In Coinbase’s Q1 2022 Form 10-Q filing with the SEC, the company added a risk disclosure that sent shockwaves through the market:
“Because custodially held crypto assets may be considered to be the property of a bankruptcy estate, in the event of a bankruptcy, the crypto assets we hold in custody on behalf of our customers could be subject to bankruptcy proceedings and such customers could be treated as our general unsecured creditors.”
Why did Coinbase insert that warning? Because earlier in 2022, the SEC had issued Staff Accounting Bulletin No. 121 (SAB 121), which required public companies holding crypto assets on behalf of platform users to record a “safeguarding liability” and a corresponding “safeguarding asset” directly on their corporate balance sheets.
Fast-forward to the recent regulatory shift. Following the change in SEC leadership, the SEC rescinded SAB 121. As detailed in Livemint’s report on Coinbase shifting customer crypto off its balance sheet, Coinbase immediately removed roughly 273 billion USD of customer safeguarding assets and liabilities from its balance sheet, dropping its reported total assets from 291 billion USD down to 23 billion USD.
From my perspective as a former banker, rescinding SAB 121 was a massive victory for traditional banks wanting to enter crypto custody, because bank regulators calculate required capital reserves as a percentage of total on-balance-sheet assets. However, accounting treatment is not bankruptcy law. As the Livemint analysis points out, even after moving those 273 billion USD of customer tokens off its balance sheet, Coinbase kept the exact same bankruptcy warning in its annual report disclosures, explicitly cautioning investors that due to the novelty of crypto assets, courts have still not definitively tested this treatment for custodied retail crypto assets.
In the United States, institutional custodians try to insulate clients from this risk by opting into Article 8 of the Uniform Commercial Code (UCC) (treating custodied digital assets as “financial assets” credited to a “securities account” held by a “securities intermediary”) or relying on the newer UCC Article 12 governing Controllable Electronic Records (CERs). Under UCC Article 8-503, financial assets held by an intermediary for entitlement holders are explicitly not property of the intermediary and are immune to claims of the intermediary’s general creditors. However, if an exchange suffers a shortfall in its omnibus wallets or fails to maintain strict 1-to-1 segregation across sub-ledgers, retail users are right back in bankruptcy court fighting over whatever remains in the pool.
Under the Hood: Cryptographic Control vs. Custodial Database Permissions
True non-custodial ownership eliminates third-party bankruptcy risk by replacing contractual promises with local cryptographic key derivation and on-chain script execution that no corporate administrator or bankruptcy trustee can freeze.
When you transition from a custodial exchange account to a non-custodial wallet (such as a hardware wallet like Trezor or Coldcard, or a self-custodial software wallet like Sparrow, MetaMask, or Rabby), you change both the technical architecture and the legal status of your money. You are no longer a creditor holding an IOU; you are the direct bearer of the cryptographic secret required to satisfy the blockchain’s spending conditions.
How Non-Custodial Key Derivation Works (BIP-39, BIP-32, and BIP-84)
In a non-custodial wallet, your ownership begins with 128 to 256 bits of high-grade hardware entropy (randomness), encoded into a 12-word or 24-word English recovery phrase under the BIP-39 standard. That mnemonic phrase passes through the PBKDF2 key-stretching function (using 2,048 rounds of HMAC-SHA512) to produce a 512-bit master seed.
From that master seed, your wallet uses BIP-32 (Hierarchical Deterministic wallets) and BIP-84 (for Native SegWit bc1q addresses) to deterministically derive child private keys and public addresses along a standardized derivation path:
m / 84' / 0' / 0' / 0 / 0
|   |     |    |    |   |
|   |     |    |    |   +-- Address Index (0 = first receiving address)
|   |     |    |    +------ Change Flag (0 = external receiving, 1 = internal change)
|   |     |    +----------- Account Index (Hardened account #0)
|   |     +---------------- Coin Type (0' = Bitcoin Mainnet, 60' = Ethereum)
|   +---------------------- Purpose (84' = BIP-84 Native SegWit P2WPKH)
+-------------------------- Master Private Key Node
Because hardened derivation (') uses the parent private key in the hash function, nobody can determine your master key from a leaked public key. More importantly, the private key never leaves your physical device. When you want to spend your funds, your computer constructs an unsigned transaction (or a Partially Signed Bitcoin Transaction, PSBT, under BIP-174), passes it to your hardware device over USB, air-gapped QR code, or microSD card, and the hardware chip signs the hash locally using the secp256k1 elliptic curve algorithm.
Verifying Non-Custodial Control via CLI
If you run your own Bitcoin node, you can verify the exact difference between an address where your wallet holds the signing keys versus a watch-only or custodial address using bitcoin-cli getaddressinfo:
bitcoin-cli getaddressinfo "bc1q3uazk8zdtehh4z6up502s36tt4ha0u6s7239r"Look closely at the ismine, solvable, and hdkeypath fields in the JSON output:
{
  "address": "bc1q3uazk8zdtehh4z6up502s36tt4ha0u6s7239r",
  "scriptPubKey": "00148f3a2b1c4d5e6f7a8b9c0d1e2f3a4b5c6d7e8f9a",
  "ismine": true,
  "solvable": true,
  "desc": "wpkh([d34db33f/84'/0'/0'/0/0]0279be667ef9dcbbac55a06295ce870b07029bfcdb2dce28d959f2815b16f81798)#x8k2m9p1",
  "iswatchonly": false,
  "isscript": false,
  "iswitness": true,
  "witness_version": 0,
  "witness_program": "8f3a2b1c4d5e6f7a8b9c0d1e2f3a4b5c6d7e8f9a",
  "pubkey": "0279be667ef9dcbbac55a06295ce870b07029bfcdb2dce28d959f2815b16f81798",
  "ischange": false,
  "timestamp": 1760918400,
  "hdkeypath": "m/84'/0'/0'/0/0",
  "hdseedid": "a1b2c3d4e5f60718293a4b5c6d7e8f9a0b1c2d3e",
  "hdmasterfingerprint": "d34db33f"
}
When "ismine": true and "iswatchonly": false appear on a non-custodial wallet backed by your own hardware signer, no bankruptcy court automatic stay can stop you from broadcasting a signed transaction to the peer-to-peer mempool. Even if the hardware manufacturer (like Ledger or Trezor) or the wallet software company (like MetaMask) files for Chapter 7 liquidation tomorrow morning, your funds are completely unaffected. You can simply enter your 24-word BIP-39 seed phrase into any compatible open-source wallet or construct raw transactions directly against your own node.
One critical caveat for stablecoin holders: while holding USDC or USDT in a non-custodial wallet protects you from exchange bankruptcy, you still carry issuer smart-contract risk. Centralized stablecoin contracts (such as Circle’s FiatTokenV2_2 on Ethereum) contain an administrative blacklist(address _account) function that allows the issuer to freeze specific addresses at the smart-contract level pursuant to law enforcement orders. For censorship-resistant, bankruptcy-proof self-custody, native Layer 1 assets like BTC and ETH remain the only instruments free of both custodian balance-sheet risk and issuer blacklist functions.
Auditing Your Custody Risk: A Practical Framework for Crypto Holders
Protecting your digital wealth requires auditing exchange Terms of Service for four specific legal red flags and implementing a tiered architecture that separates fiat execution rails from long-term self-custody storage.
After two and a half decades of reviewing institutional custody contracts, I never take a platform’s marketing homepage at face value. Before leaving a single dollar or satoshi on any platform, open their Terms of Service (User Agreement), press Ctrl + F (or Cmd + F), and search for these four specific legal clauses:
- Title and Ownership Transfer (
"title","ownership","grant","transfer"): Does the agreement explicitly state that title to your digital assets remains with you at all times and that the platform acts solely as a bailee or custodian? If a yield, staking, or margin clause states that you transfer “all right, title, and interest” to the platform, you are legally an unsecured lender. - Rehypothecation and Pledging (
"rehypothecate","pledge","loan","encumber"): Does the platform reserve the right to lend, pledge, or rehypothecate your assets? If so, your coins are leaving the vault to generate yield for the house, introducing fatal counterparty risk. - Omnibus Commingling vs. Segregation (
"omnibus","commingle","pooled","segregated"): Check whether your assets are held in pooled omnibus wallets or individually segregated on-chain vaults. Also check whether the platform specifies that custodial accounts are governed by UCC Article 8 as financial assets exempt from claims of the custodian’s general creditors. - Corporate Structure and Charter Type (
"trust company","SPDI","charter"): As noted in CCN’s overview of cryptocurrency exchange bankruptcy timelines, understanding regulatory structure is vital because court recoveries can take nearly a decade (as seen with Mt. Gox). A state-chartered limited purpose trust company (such as a New York Department of Financial Services qualified custodian) or a Wyoming Special Purpose Depository Institution (SPDI) operates under strict statutory asset-segregation and insolvency rules that differ significantly from an ordinary Delaware LLC operating a retail trading app.
The 3-Tier Custody Architecture I Use and Recommend
You do not have to choose between avoiding centralized exchanges entirely and leaving your life savings exposed to a Chapter 11 freeze. Treat centralized exchanges the exact same way traditional bond traders treat clearinghouses: as temporary execution pipes, never as permanent storage vaults.
- Tier 1: The Fiat Execution Pipe (Custodial Exchange, 0% to 5% of Portfolio): Use regulated exchanges (such as Coinbase or Kraken) strictly for converting fiat currency into crypto and executing limit orders. Once your fiat deposit clears the bank ACH hold, withdraw the purchased crypto to your own wallet immediately.
- Tier 2: Active Web3 & Spending Wallet (Non-Custodial Hardware-Backed Single-Sig, 5% to 15% of Portfolio): Keep medium-term operational balances in a non-custodial wallet paired with a dedicated hardware signing device (never typing your seed phrase on an internet-connected keyboard).
- Tier 3: Long-Term Vault (Multi-Signature or Timelocked Cold Storage, 80% to 95% of Portfolio): For significant wealth, eliminate single points of failure by using a 2-of-3 non-custodial multisig quorum (for example, using Sparrow Wallet for Bitcoin or a Safe smart account for Ethereum across three geographically separated hardware keys from different manufacturers).
In traditional finance, you are forced to trust intermediaries and rely on government insurance programs to clean up the mess when bankers mismanage their balance sheets. In crypto, the protocol gives you the power to be your own clearinghouse and your own vault. Use exchanges for liquidity, verify the fine print like a bank auditor, and hold your own keys.
Sponsored Partner: Volet.com
Looking for a simple, everyday way to buy, hold, and sell cryptocurrencies alongside your traditional currencies and payment cards?
- Read my full breakdown: Complete Volet Review on DoraMilen.com
- Get started right away: Open your free Volet account using my referral link